A home can be insured for what looked like a reasonable reconstruction estimate at renewal and still be underinsured after a major catastrophe. Labor shortages, debris removal, contractor demand, material prices and updated building requirements can push rebuilding costs higher after a widespread event. That is the problem extended and guaranteed replacement-cost features are designed to address.
The first distinction is between the settlement basis and the maximum amount available. Standard replacement-cost coverage describes how a covered loss is valued: generally without deducting physical depreciation once policy conditions are met. It does not automatically mean there is no cap. The dwelling limit still matters unless an endorsement extends or removes that cap for covered rebuilding costs.
Replacement cost, extended replacement cost and guaranteed replacement cost
| Coverage concept | What it generally does | What to verify |
|---|---|---|
| Replacement cost | Values covered repairs or rebuilding without a depreciation deduction, subject to policy terms and limits | Dwelling limit, claim-payment conditions and exclusions |
| Extended replacement cost | Adds a stated percentage or fixed amount above the dwelling limit | The extension percentage/dollar amount and when it applies |
| Guaranteed replacement cost | Is intended to cover the covered cost to rebuild even above the stated dwelling limit | Eligibility, required updates, policy conditions and excluded costs |
California’s Department of Insurance provides a useful consumer definition: its residential guide says a policy cannot be sold there as guaranteed replacement cost unless it will pay to completely rebuild the home regardless of the coverage limit. California disclosures also describe extended replacement cost as additional coverage above the dwelling limit up to a stated percentage or specific dollar amount. Those definitions are helpful for understanding the concepts, but consumers in every state should read their own policy and state rules.
Why the dwelling limit still matters
Even with an extension, the dwelling limit is the starting point. Suppose a home carries a $500,000 Coverage A limit and an endorsement provides 25% extended replacement cost. The nominal ceiling for covered dwelling rebuilding could be $625,000, subject to the policy wording. If the actual covered rebuild costs $700,000, the extension may still leave a gap. A guaranteed form may respond differently, but it can contain conditions that must be satisfied.
That is why lowering the dwelling limit simply to reduce premium can be dangerous. A percentage extension calculated from an artificially low base can still be inadequate. Start with a realistic reconstruction estimate and treat the extension as a buffer—not as permission to underinsure the structure.
For the underlying valuation concepts, see our guide to replacement cost vs. actual cash value and our homeowners insurance limit checklist.
What can cause rebuilding costs to exceed the estimate?
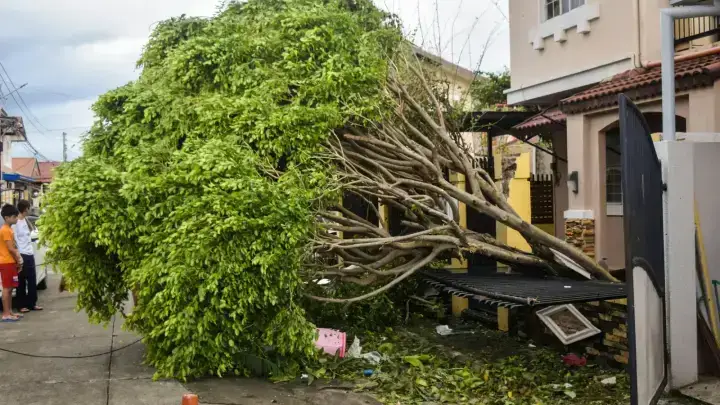
- Post-catastrophe demand surge. A wildfire, hurricane or tornado can create simultaneous demand for contractors and materials.
- Labor and material inflation. A replacement-cost estimate is a snapshot; construction pricing changes.
- Debris removal and site conditions. Total-loss reconstruction can involve expenses not obvious from square-foot estimates.
- Special features. Custom millwork, masonry, older architectural details and high-end finishes can be underestimated.
- Building-code changes. A rebuild may need to comply with codes that did not apply when the original home was built.
Building-code costs deserve separate attention because an extended dwelling limit does not necessarily create ordinance-or-law coverage. Read our guide to ordinance or law coverage to understand why code-upgrade protection can be a distinct limit or endorsement.
Common conditions to check before relying on an endorsement
Policy forms differ, but extended or guaranteed replacement provisions may depend on the insured maintaining an adequate base limit, reporting renovations, accepting inflation adjustments, insuring the dwelling to the insurer’s replacement-cost estimate or rebuilding after a covered loss. Do not assume the extra limit is automatic in every scenario.
Ask the insurer or agent to identify the exact endorsement form number and explain: the base dwelling limit; the extension percentage or maximum; how detached structures and personal property are handled; whether building-code costs are inside or outside the extension; whether debris removal has a separate allowance; and what happens if you buy another home instead of rebuilding at the same site.
How to compare two homeowners quotes correctly
Two quotes with the same $500,000 dwelling limit can provide materially different protection. One might have no extension, another a 25% extension, and another a guaranteed-replacement endorsement. Deductibles, roof settlement, water limitations and catastrophe deductibles can also differ. Compare the full contract structure, not just the premium and Coverage A number.
| Quote question | Why it matters |
|---|---|
| What is the dwelling limit? | It is the base amount used by most replacement-cost structures |
| Is there an extension? | It can add a percentage or dollar buffer after a covered loss |
| Is coverage actually guaranteed? | The label should match the policy form and state rules |
| Is ordinance or law separate? | Code-upgrade costs may have their own limit |
| What must I do to keep the endorsement? | Renovation reporting and valuation updates can be important conditions |
What happens when you disagree about the amount of loss?
Extended or guaranteed replacement cost does not eliminate claim disagreements. The parties can still dispute the scope of damage, repair method or reconstruction price. Some homeowners policies include an appraisal process for amount-of-loss disputes. Our guide to the homeowners insurance appraisal clause explains what that mechanism can and cannot decide.
Questions to ask at every renewal
- What rebuilding-cost estimate did the insurer use this year?
- What construction details are in that estimate, and are they accurate?
- Did a renovation, addition, solar installation or major finish upgrade change the replacement cost?
- What is the exact extended or guaranteed replacement-cost endorsement?
- Are code upgrades, debris removal and temporary living expenses subject to separate limits?
- Could I fund the deductible and any amount above the available reconstruction protection?
Frequently asked questions
Is extended replacement cost the same as guaranteed replacement cost?
No. Extended replacement cost normally adds a defined amount above the dwelling limit. Guaranteed replacement cost is intended to cover the covered rebuilding cost even above the stated limit, subject to the policy’s conditions.
Does replacement cost mean my insurer will pay any amount to rebuild?
No. Replacement cost describes a valuation basis. The declarations, limits and endorsements determine how much protection is available.
Should I intentionally set a low dwelling limit if I have a 25% extension?
That can create serious underinsurance. The percentage extension is usually calculated from the base dwelling limit, so an inadequate base can produce an inadequate total.
Does extended replacement cost automatically pay for building-code upgrades?
Not necessarily. Ordinance or law coverage can be separate. Check the policy and endorsement limits.
Sources and further reading
Reviewed October 5, 2026. Definitions and claim-payment rules vary by policy form and state. This guide explains coverage concepts and is not a substitute for the actual contract.