
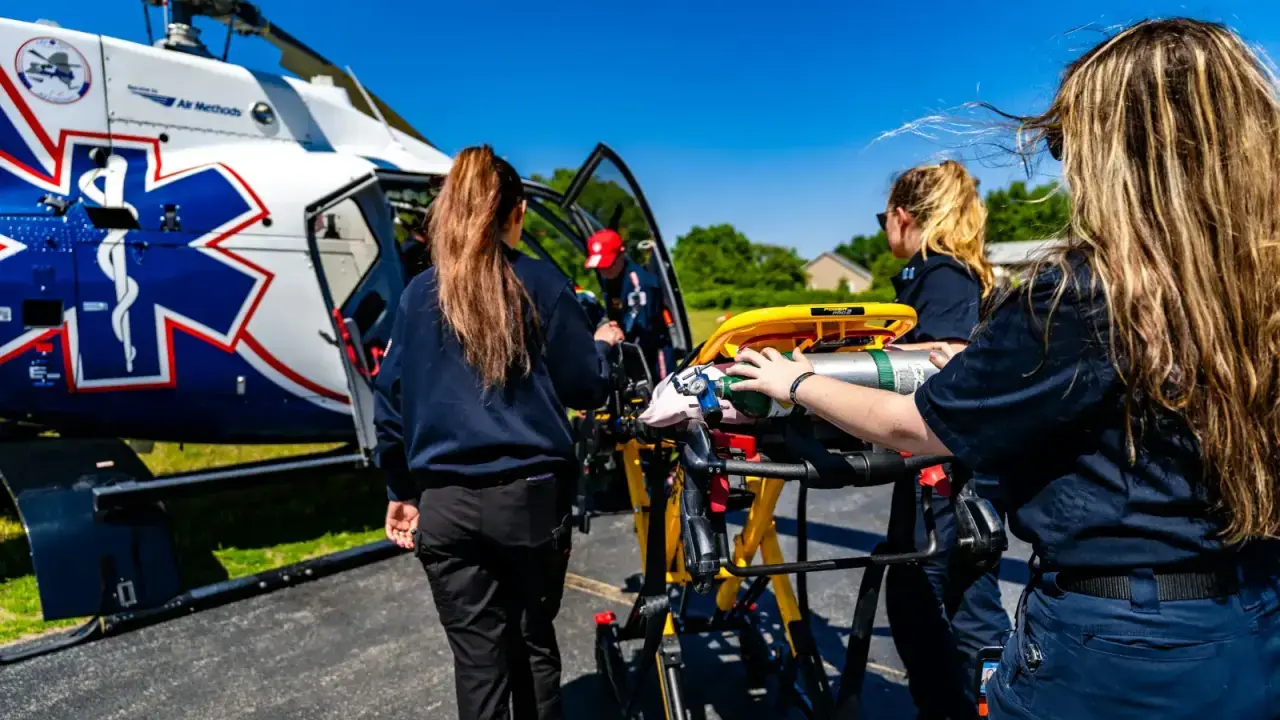
A broken leg in a major city and a life-threatening illness on a remote island create very different travel risks. The hospital bill is only one concern. A traveler may need a ground ambulance, medical escort, helicopter, air ambulance or transfer to another country with suitable care.
The U.S. Department of State warns that the U.S. government does not pay medical bills for citizens abroad and recommends considering travel health and medical evacuation coverage. Its current guidance notes that air-ambulance evacuation back to the United States can cost roughly $20,000 to $200,000 depending on location and medical condition. Actual costs can be lower or higher.
What medical evacuation insurance can cover
Coverage varies, but a policy can include medically necessary transportation from the place of illness or injury to the nearest appropriate medical facility. Some plans may also cover a later transfer to a different hospital, a medical escort on a commercial flight or transportation back to the traveler’s home country when medically appropriate.
Related assistance services can be just as important as the dollar limit. A 24-hour assistance team may coordinate hospitals, transportation providers and medical records. Some policies require the assistance company to approve and arrange an evacuation before costs are covered.
Medical evacuation vs. travel medical insurance
| Coverage | Main purpose |
|---|---|
| Travel medical | Eligible doctor, hospital, medication and emergency treatment costs during the trip |
| Medical evacuation | Eligible transportation to an appropriate medical facility |
| Trip cancellation | Eligible prepaid nonrefundable trip costs when cancellation is caused by a covered reason |
| Repatriation of remains | Eligible transportation of remains after a covered death, if included |
A plan can bundle several of these benefits, but they should not be assumed from the product name alone.
Who may have the greatest need?
- Travelers visiting remote areas, islands or destinations with limited specialist care.
- Adventure travelers engaging in activities such as trekking, skiing, diving or remote touring.
- Older travelers or people with medical conditions who may need specialist treatment.
- Cruise passengers who could require transfer from a ship or port to a capable hospital.
- Travelers whose domestic health plan provides little or no overseas coverage.
“Nearest adequate facility” vs. “hospital of your choice”
This is one of the most important wording differences. Many policies are designed to move the traveler to the nearest facility that the assistance provider considers medically appropriate. That is not the same as paying to fly the traveler directly home or to a preferred hospital.
Some higher-end products offer broader transport or membership-style benefits, but those should be confirmed in writing. Marketing phrases such as “evacuation home” can have medical-necessity and approval conditions.
What can cause an evacuation claim to be denied?
Common issues can include lack of preauthorization, an excluded activity, intoxication exclusions, traveling against medical advice, an uncovered pre-existing condition, a destination excluded by the policy, a loss related to war or civil unrest, or a transport that the insurer does not consider medically necessary.
Policy language differs substantially. Travelers should review adventure-sports provisions, altitude restrictions, motorcycle or scooter conditions and any requirement to use the insurer’s assistance network.
How much medical evacuation coverage is enough?
There is no single ideal limit. Consider distance from advanced medical care, destination infrastructure, planned activities and whether the plan could require international air ambulance transportation. A short city break in Western Europe presents a different evacuation exposure from an expedition in a remote region.
The State Department’s cost example shows why low limits can be problematic in severe cases. The decision should be based on realistic worst-case transportation, not the average cost of a routine clinic visit.
Before buying a policy, ask these questions
- Who decides whether evacuation is medically necessary?
- Does the plan transport me to the nearest adequate facility or potentially home?
- Must the assistance company arrange the transport?
- What is the maximum evacuation limit?
- Are my planned activities covered?
- How are pre-existing conditions handled?
- Is repatriation of remains included?
- Is there a 24-hour emergency assistance number?
What if your regular U.S. health plan covers care abroad?
That does not automatically mean it pays for medical evacuation. The State Department specifically notes that many health plans that cover ordinary medical costs abroad do not pay to bring a traveler back to the United States by special air ambulance. Check both medical-treatment coverage and transportation coverage separately.
Frequently asked questions
Does Medicare cover medical evacuation abroad?
Medicare generally does not cover health care outside the United States except in limited statutory situations. Travelers should review current Medicare rules and separate travel coverage.
Will evacuation insurance always fly me home?
No. Many plans focus on transport to the nearest medically appropriate facility and require the assistance provider’s approval.
Can I buy evacuation coverage without trip cancellation coverage?
Some products offer stand-alone or primarily medical/evacuation benefits, while comprehensive travel plans bundle multiple protections.
Does travel insurance cover helicopter rescue?
It can in some circumstances, but medical necessity, activity exclusions, geographic restrictions and preauthorization requirements matter.
Sources & further reading
Reviewed October 2, 2026. Travel insurance benefits, exclusions and evacuation decisions vary by policy and destination; always review the certificate and emergency-assistance procedures before departure.



