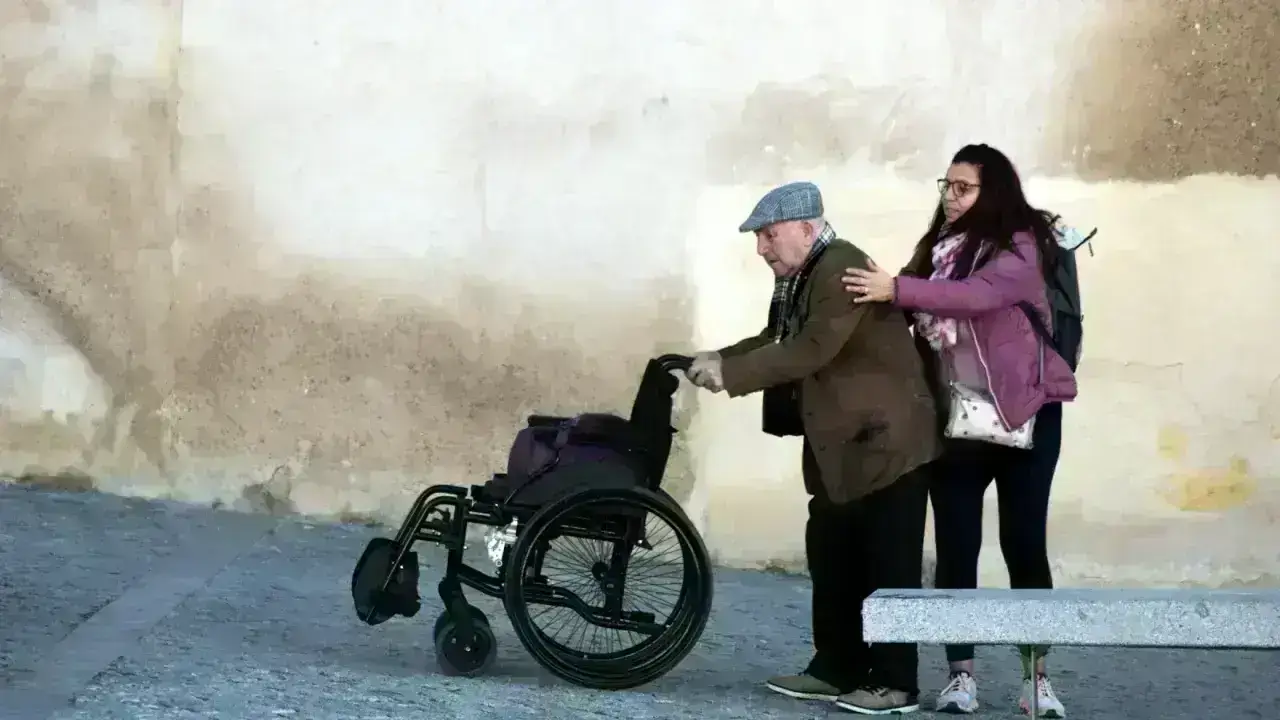
Long-term care is different from ordinary medical treatment. The need often arises because a person can no longer safely perform everyday activities such as bathing, dressing or eating without assistance. That support can continue for months or years and may be provided at home or in a residential setting.
The NAIC notes that the U.S. long-term care insurance market has evolved significantly and that policies can include home health care, respite care, hospice, personal care in the home, assisted living and adult day care. Public programs such as Medicare and Medicaid also cover certain services, but eligibility and scope are different from private long-term care insurance.
What usually triggers benefits?
Many tax-qualified long-term care policies use functional or cognitive benefit triggers. A common structure is inability to perform a specified number of activities of daily living (ADLs) without substantial assistance, or severe cognitive impairment. Exact language matters because the contract determines when benefits begin.
Key policy terms to understand
| Term | What it means |
|---|---|
| Daily/monthly benefit | The maximum amount or reimbursement available during a benefit period |
| Benefit period / pool | How long benefits may last or the total amount available |
| Elimination period | A waiting period before covered benefits become payable |
| Inflation protection | A feature designed to increase benefits over time |
| Nonforfeiture | Possible reduced benefits if a policy lapses after specified conditions |
Home care vs. facility care
Modern policies may cover more than nursing homes. Depending on the contract, eligible services can include home health care, personal care, assisted living, adult day care, respite care and hospice. Buyers should check whether benefit limits differ by setting.
Why age and health matter at purchase
Long-term care insurance is medically underwritten. Applying earlier can mean a better chance of qualifying, but it also means paying premiums for a longer period. Waiting can reduce the number of years premiums are paid but may increase cost or make coverage unavailable if health changes.
Premium increases and reduced benefit options
Unlike level-premium guarantees on some other products, long-term care insurance premiums can be subject to approved class-wide rate increases under state rules. The NAIC has developed multistate approaches and guidance around rate reviews and reduced-benefit options. Policyholders facing an increase should compare available options carefully before cancelling coverage.
Questions to ask before buying
- What exact event triggers benefits?
- How long is the elimination period and how is it counted?
- Is care at home covered on the same basis as facility care?
- What inflation protection is available?
- Is the benefit reimbursed based on expenses or paid as an indemnity?
- What happens if premiums rise?
- Are informal caregivers or family-provided services eligible?
- What exclusions and pre-existing-condition provisions apply?
Long-term care insurance vs. Medicare and Medicaid
Medicare is primarily a health insurance program and does not function as unlimited custodial long-term care insurance. Medicaid can cover long-term services and supports for eligible people, but financial and functional eligibility rules apply and vary by state. Private LTC insurance is a separate planning tool.
Frequently asked questions
Does long-term care insurance only cover nursing homes?
No. Many policies can cover home care, assisted living, adult day care and other qualifying services.
What is an elimination period?
It is a waiting period defined by the policy before benefits become payable.
Can premiums increase?
They can, subject to policy terms and state regulatory requirements. Long-term care rate increases have been a major regulatory issue.
Sources & further reading
Reviewed against NAIC material in September 2026. This is general educational information, not medical, tax or financial planning advice.