
Home insurance decisions in Australia have become increasingly connected to rebuilding costs and natural hazards. ASIC’s Moneysmart guidance emphasises that the amount insured should reflect the cost to rebuild the home and replace belongings, and warns that underinsurance can leave households with a significant shortfall after a major loss.
Building vs. contents insurance
| Cover | Designed for | Examples |
|---|---|---|
| Building insurance | The house and fixed parts of the property | Structure, plumbing, built-in cabinetry, and often specified other structures |
| Contents insurance | Household items and personal belongings | Furniture, clothes, appliances, computers and other movable property |
Moneysmart notes that apartment or strata owners may not need separate building insurance if the body corporate insures the building, but they remain responsible for their contents and should understand the strata arrangement.
Market value is not rebuild cost
A common mistake is using a property’s sale price as the insurance target. The land itself is not being rebuilt after a fire or storm. Rebuild cost can include demolition, debris removal, labour, materials, professional fees, council requirements and post-disaster cost inflation.
A property can therefore fall in market value while its rebuild cost rises—or the reverse. Insurance calculations need to focus on the physical cost of restoration.
What does underinsurance mean?
Moneysmart defines underinsurance as having insufficient cover to fully rebuild, repair or replace what is lost. This can occur when the sum insured is guessed, not updated after renovations, or fails to keep pace with construction inflation.
Some policies can contain averaging or coinsurance provisions that affect partial claims when the property is materially underinsured. Policy wording matters: a shortfall may do more than cap a total loss at the sum insured.
Natural hazards: ask what is actually insured
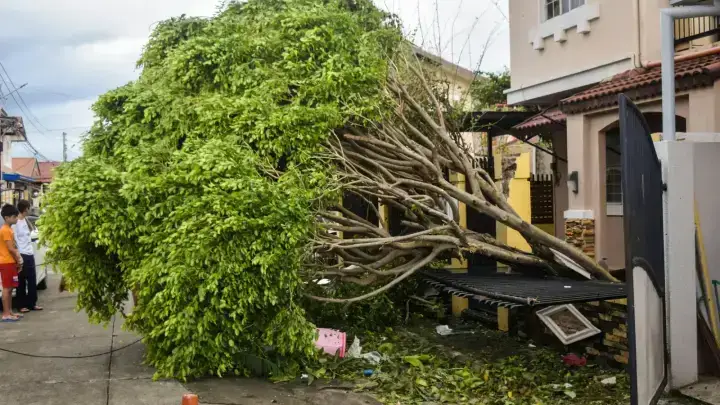
Australia faces flood, storm, cyclone, bushfire and other catastrophe exposures. Moneysmart recommends checking local information such as flood mapping, historical flood records, cyclone risk and Bushfire Attack Level where relevant. An insured event must be defined by the policy, and exclusions can differ.
- Check the policy definition of flood, storm, action of the sea and other water events.
- Review cyclone or named-event excesses where relevant.
- Understand bushfire-related conditions, rebuilding requirements and local risk information.
- Check whether temporary accommodation is inside or additional to the sum insured.
- Verify limits for jewelry, electronics, collections and portable valuables.
Replacement value of contents is easy to underestimate
A room-by-room inventory often produces a much higher number than an initial guess. Furniture, clothing, kitchen equipment, electronics, tools and everyday possessions accumulate over years. Moneysmart recommends documenting belongings and reviewing the amount regularly.
Six checks before renewal
- Recalculate the building rebuild cost with a current calculator or professional estimate where appropriate.
- Add major renovations and upgrades completed since the last review.
- Recalculate household contents at current replacement prices.
- Review hazard-specific definitions, excesses and exclusions.
- Check temporary accommodation and debris-removal provisions.
- Compare policy quality and claims features as well as premium.
Sum insured vs. “safety net” features
Some policies may offer extended or safety-net benefits above the sum insured under specified conditions. These features can be useful, but they should not be used as an excuse to deliberately understate the base sum insured. Read the eligibility rules and caps carefully.
Frequently asked questions
Do renters need building insurance?
The landlord is generally responsible for the building, while a renter may choose contents insurance for belongings and associated liability protection.
Do strata owners need home building insurance?
The body corporate may insure the building. Unit owners should confirm what that policy covers and insure their own contents and any owner-responsible property.
How often should I review the sum insured?
At least at renewal and after major renovations or purchases. Rebuilding and replacement costs can change quickly.
Does the cheapest policy provide the same cover?
No. Insured events, exclusions, excesses, limits and claim settlement terms can differ materially.
Sources & further reading
Reviewed against Australian Moneysmart guidance in September 2026. Insurance terms, hazard definitions and excesses vary by insurer and location.